When people think about investing, the first question that often comes to mind is, “Where should I invest my money?” Should it be mutual funds, stocks, fixed deposits, bonds, gold or real estate? While choosing the right investment products is important, there is a more fundamental question that should come first: What are you investing for?
This is where financial planning becomes important. Investment selection should ideally be a part of a broader financial plan rather than the starting point. A well-designed financial plan connects your income, expenses, financial goals, risk tolerance, insurance needs and investments into a structured strategy.
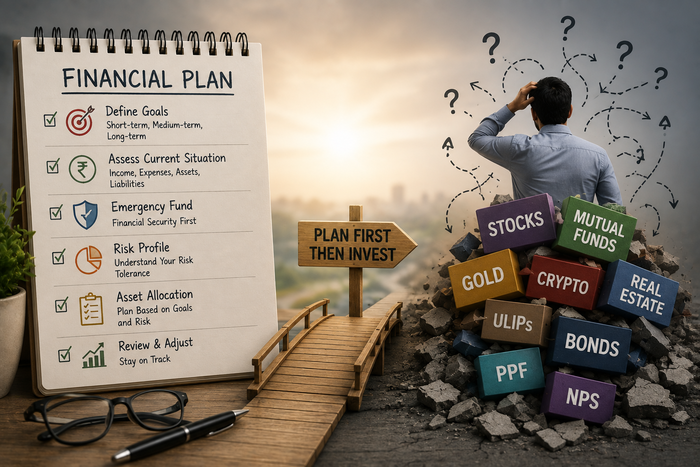
What Is Financial Planning?
Financial planning is the process of understanding your current financial position and creating a roadmap for achieving your short-term and long-term goals. These goals could include buying a home, funding a child’s education, planning a wedding, building an emergency fund, starting a business or preparing for retirement.
Instead of asking which investment can generate the highest return, financial planning begins by asking what you need your money to accomplish and when you will need it.
SEBI’s investor education resources similarly recommend considering factors such as financial goals, investment horizon, risk appetite, liquidity, diversification and asset allocation before making investment decisions.
Why Investment Selection Should Come Later
An investment may be excellent in isolation but unsuitable for a particular investor. For example, equities may offer significant long-term growth potential, but putting money required for a near-term financial goal entirely into volatile assets could expose the investor to unnecessary risk. Similarly, keeping all long-term wealth in low-risk instruments may not provide sufficient growth to meet goals over several decades.
The right investment therefore depends on the purpose of the money, the time available and the amount of risk that can reasonably be taken.
Financial planning provides this context before individual products are selected.
1. It Helps Define Clear Financial Goals
A portfolio without a goal can easily become a collection of random investments. Financial planning helps convert broad aspirations into measurable objectives. Instead of simply saying “I want to build wealth,” an investor can define specific goals such as building a retirement corpus by a certain age or accumulating a particular amount for a child’s higher education.
Once goals are clearly defined, it becomes easier to determine how much needs to be invested and for how long.
2. It Determines Your Investment Time Horizon
Different financial goals have different timelines. Money required within a few years may need a different strategy from money that will not be needed for 15 or 20 years. A longer investment horizon can provide greater ability to withstand short-term market fluctuations, while shorter-term requirements may call for greater emphasis on stability and liquidity.
Understanding the investment horizon before selecting products helps prevent a mismatch between the investment and the goal.
3. It Helps Determine the Right Risk Level
Risk tolerance is another crucial part of investment planning. Two people with identical incomes may have completely different financial circumstances and attitudes toward risk. One may be comfortable with significant market fluctuations, while another may prefer greater stability.
Financial planning considers both the investor’s willingness and ability to take risk before determining an appropriate investment strategy.
4. It Creates an Appropriate Asset Allocation
One of the biggest advantages of financial planning is that it shifts attention from individual products to asset allocation. Instead of asking, “Which mutual fund should I buy?” the more important question becomes, “How should my overall portfolio be divided across different asset classes?”
Depending on the investor’s goals and circumstances, this could involve a combination of equity, fixed income, gold, cash and other suitable assets.
SEBI notes that asset allocation should be considered in relation to an investor’s financial goals, risk tolerance and investment horizon.
5. It Brings Insurance and Emergency Planning Into the Picture
Investment planning should not happen in isolation from financial protection. Before aggressively investing for long-term wealth creation, investors should consider whether they have adequate emergency savings and appropriate insurance protection. An unexpected medical expense, job loss or other financial emergency can force someone to liquidate investments at an inconvenient time.
SEBI’s investor guidance specifically highlights maintaining an emergency fund and having insurance coverage as important considerations before investing.
6. It Reduces Emotion-Driven Investment Decisions
Market movements can influence investor behaviour. When markets rise sharply, investors may feel tempted to chase recent returns. When markets fall, fear may encourage them to exit investments prematurely. A financial plan provides a framework for making decisions based on predetermined goals rather than short-term market sentiment.
This is also where professional financial planning can add value. For example, HappyWise Financial Services focuses on goal-based financial direction, asset allocation and periodic portfolio reviews, helping investors connect their investment decisions with their broader financial objectives.
Financial Planning First, Investment Selection Second
Investment selection is undoubtedly an important part of building wealth, but it should not happen in isolation.
The logical sequence is simple:
Understand your financial position → define your goals → determine your timelines → assess risk → establish asset allocation → select suitable investments → review and rebalance regularly.
This approach makes investing more purposeful. Instead of constantly searching for the “best investment,” you build a portfolio designed around what your money actually needs to achieve.
Ultimately, successful investing is not just about selecting products with attractive returns. It is about putting the right money, into the right investments, for the right goals, at the right level of risk. That is why financial planning should come before investment selection.