
A portfolio designed for long-term wealth creation may not be appropriate for money that you will need in the near future.
This is why good financial planning begins with identifying goals before selecting investments.
Risk Tolerance Is Personal
Two investors can look at the same market decline and react completely differently. One investor may be comfortable seeing their portfolio fall temporarily because they have a long investment horizon. Another may panic and sell because they need the money soon or are uncomfortable with volatility.
This is why simply copying someone’s allocation to equities, debt, gold or other assets can be problematic.
Your investment portfolio should reflect both your ability to take risk and your willingness to take risk.
A portfolio that is appropriate for an aggressive investor may be completely unsuitable for a conservative investor.
You Don’t Know the Complete Picture
Social media and informal investment discussions often show only part of the story. Someone may share that they earned a 30% return from a particular stock, but you may not know how much of their overall wealth was invested in it, when they purchased it, whether they have other diversified investments or how much risk they took to achieve that return.
Similarly, a screenshot of a portfolio doesn’t reveal the investor’s emergency fund, insurance coverage, outstanding loans, income or other financial assets.
Copying visible investments without understanding the invisible parts of the financial plan can lead to poor decisions.
Past Returns Do Not Guarantee Future Results
Another common mistake is assuming that an investment that performed well recently will continue performing well.
A stock, mutual fund or asset class may have delivered exceptional returns over a particular period. That does not mean the same performance will continue.
Investment decisions should therefore not be based solely on recent performance.
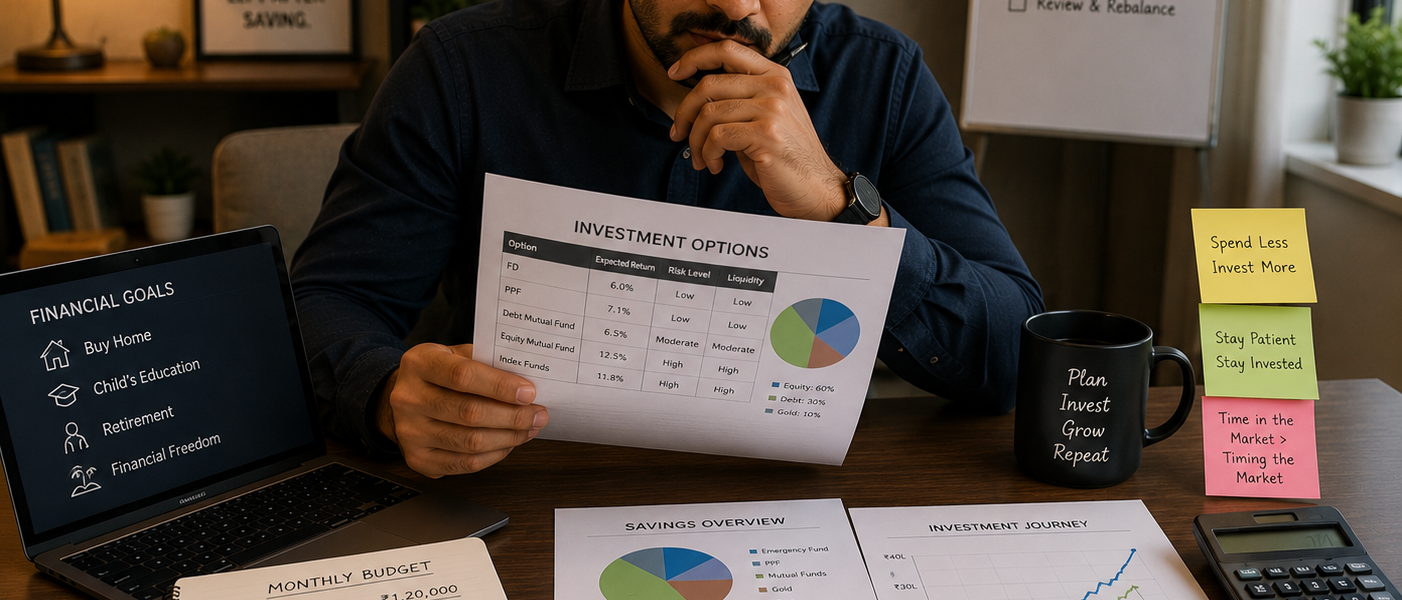
Instead, investors should consider factors such as their financial goals, investment horizon, risk profile, diversification and asset allocation.
SEBI’s investor education resources specifically highlight the importance of considering financial goals, investment horizon, risk appetite and diversification when making investment decisions.
Your Investment Horizon Changes the Right Strategy
Time is an important factor in investing.
Someone who is 25 and investing for retirement may have decades to remain invested through market cycles. Someone who is 55 and approaching retirement may have a much shorter horizon.
If the younger investor’s portfolio contains a relatively high allocation to growth-oriented assets, that allocation may not automatically be appropriate for someone nearing retirement.
The same investment can therefore have very different suitability depending on when the money will be needed.
Asset Allocation Matters More Than Individual Products
Investors often focus on finding the “best” stock or mutual fund.
But an effective investment strategy is usually about more than individual products. Asset allocation—the way your portfolio is distributed across different asset classes—can have a significant impact on overall portfolio risk and behaviour.
Instead of asking, “Which investments does this person own?”, a better question is:
“What asset allocation is appropriate for my financial goals and risk profile?”
Once that is established, individual investments can be evaluated within the larger strategy.
Copying Can Encourage Emotional Decisions
Following another person’s portfolio can also make investing more emotional.
If the person you are copying sells an investment, you may feel pressure to sell. If they suddenly move into a new asset, you may feel that you are missing an opportunity.
This can result in frequent buying and selling, chasing returns and abandoning a long-term strategy.
A personal investment plan provides an anchor during periods of market uncertainty.
Your Financial Situation Can Change
Even if someone else’s portfolio was suitable for you at one point, your own circumstances can change.
A salary increase, marriage, home loan, new child, career change or approaching retirement can alter your financial priorities.
This is why an investment portfolio should be reviewed periodically rather than treated as something that can simply be copied and forgotten.
For investors who want a structured approach, HappyWise Financial Services can help connect investment decisions with individual financial goals, risk considerations and broader financial planning rather than relying on someone else’s portfolio as a template.
Learn From Others—Don’t Blindly Copy Them
There is nothing wrong with learning from other investors. Someone else’s portfolio can introduce you to a new asset class, investment idea or financial concept. The mistake is assuming that their strategy automatically fits your circumstances.
Use other people’s experiences as information, not instructions.
Before making an investment decision, ask yourself:
What is my goal? How long will I invest? How much risk can I take? What happens if the investment falls significantly? And how does this investment fit into my overall portfolio?
The best investment portfolio is not necessarily the one that produced the highest returns for someone else.
It is the one that is designed to help you achieve your own financial goals while taking a level of risk you can realistically live with.